Key takeaways
- The best business bank account for your LLC depends on how you operate: cash handling, branch access, transaction volume, or cross-border payments.
- Keeping a separate bank account for your LLC protects your limited liability and keeps your books clean.
- Compare the full fee picture, not just the monthly fee. Wire costs and foreign exchange margins can outweigh a low or $0 headline price.
- If your LLC pays or gets paid across borders, a fintech alternative can hold multiple currencies and use local payment rails, so you avoid stacking bank wire and conversion fees.
Opening an LLC and working out which account will keep your business and personal money properly separated, without draining your profits on fees, is one of the first real hurdles founders face. This guide compares the best business bank accounts for LLCs, from traditional banks to fintech alternatives, and shows how to match the right account to the way your company actually operates.
Jump to:
• What is a business bank account for an LLC?
• Do you need a separate bank account for your LLC?
• Best business accounts for LLCs: bank and fintech options
• Fees and features at a glance: LLC account comparison
• How to choose the best business bank account for your LLC
• How to open a business bank account for your LLC
• FDIC insurance and keeping your LLC’s money secure
• Why OFX stands out for business
• Best bank accounts for LLCs FAQs
What is a business bank account for an LLC?
Picking from the best business bank accounts for LLC owners starts with knowing what a business bank account for an LLC actually is. It’s a deposit account held in your company’s legal name and Employer Identification Number (EIN), kept separate from your personal money. With 36.2 million small businesses in the US, most founders face this decision early.1
Most LLCs open a business checking account to handle everyday transactions, get a corporate card that merchants accept, and keep cash flow under control.
You can choose a traditional bank with branches, an online business bank account for LLC owners who prefer to manage everything digitally, or a fintech provider that offers business accounts without being a bank.
The structure of your company matters too. A single-member LLC business account works much like a sole proprietor’s, while a multi-member LLC usually needs an ownership agreement on file. Either way, this account becomes the financial hub for your business.
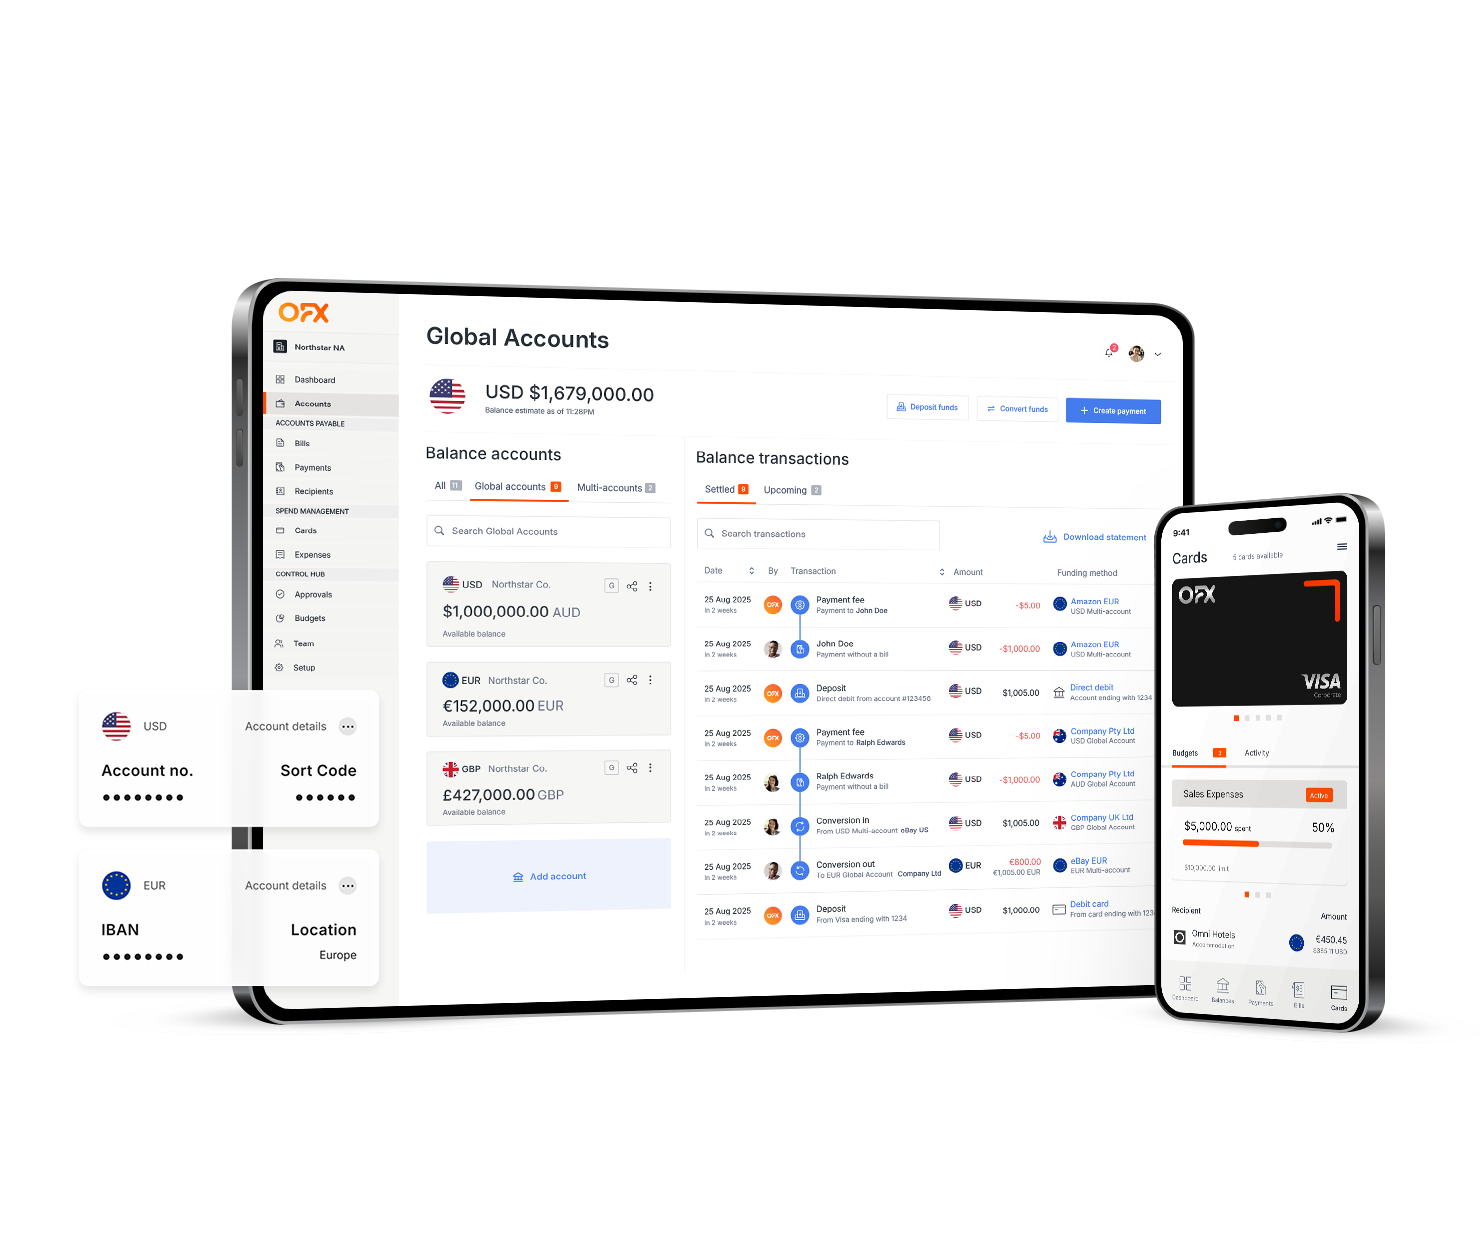
OFX Global Business Account
Receive, hold, convert and send funds across a wide range of currencies, reduce costs and gain greater control over your international payments.
Do you need a separate bank account for your LLC?
Yes. A separate bank account for your LLC keeps business funds separate from personal funds, which can help preserve the limited personal liability protection an LLC is designed to provide.2
Maintaining a clear separation between your LLC and your personal finances helps reinforce the LLC’s status as a separate legal entity.3
There is a practical upside too. A clean business bank account for LLC bookkeeping makes tax time, reconciliation, and investor reporting far simpler. It also presents a more professional face to clients and suppliers.
Best business accounts for LLCs: bank and fintech options
There isn’t one business account that’s right for every LLC. The best choice depends on how your business operates, so we’ve grouped the leading providers by where they offer the most value. Where relevant, we’ve distinguished between traditional banks and fintech providers, such as OFX and Wise.
OFX — best for international payments and multi-currency accounts.
OFX is a modern fintech alternative to traditional international business bank accounts. It lets your LLC hold and manage 30+ currencies and get local account details in USD, CAD, EUR, and GBP, so you can get paid like a local across 180+ countries.4
Where available, OFX uses local payment rails instead of relying solely on SWIFT, helping reduce transfer costs and improve payment efficiency. There are no setup fees, no transfer fees, and no minimum balance requirements.
The platform also integrates with QuickBooks Online and Xero, registration takes under 10 minutes, and its Corporate Cards earn cashback on eligible card spend (terms apply; availability varies by region). OFX is registered as a Money Services Business with the Financial Crimes Enforcement Network (FinCEN) and is licensed as a money transmitter by the relevant state regulatory agencies in the United States (NMLS #1021624).5
Bluevine — best for online high-yield business checking.
Bluevine is an online business banking provider built around an interest-earning checking account. Its Standard plan has a $0 monthly fee and eligible customers can earn up to 1.3% APY on qualifying balances by meeting monthly eligibility requirements.6 Deposits are eligible for FDIC insurance up to $3 million through Bluevine’s partner bank sweep program.6 Businesses looking for additional features can upgrade to the Premier plan for $95 per month6. It’s a strong pick if you want yield on your balance and prefer to bank entirely online.
Chase — best for branch access and traditional banking.
Chase is a good option for LLC’s that highly value in-person banking. Its nationwide branch network makes it easy to deposit cash, access face-to-face support, and manage everyday banking through a traditional institution.
Business Complete Banking has a $15 monthly service fee, with opportunities to waive the fee if you meet Chase’s eligibility requirements.7 Upgrading to the Performance tier will set you back $40 per month8. As a traditional bank, Chase applies wire fees and foreign transaction fees on international activity, so factor those in if you send money abroad. Accounts are USD only and FDIC insured.
Mercury — best for startups
Mercury is a fintech that’s popular with venture-backed startups. It charges $0 in monthly fees, with paid plans available for businesses that need additional features and support.9
Mercury is built primarily for businesses operating in US dollars. Companies with significant international payment needs may choose to pair it with a provider that offers multi-currency accounts and foreign exchange services. It is USD-focused, so heavy cross-border payers may want to pair it with a multi-currency provider.
Novo — best for freelancers and solopreneurs
Novo is a fintech offering a free business checking account for LLC owners who are freelancers or solo operators. It has no monthly fees and no minimums10, includes free standard ACH and free incoming wires, and charges up to $30 to send a domestic wire11. Built-in invoicing makes it easy to get paid.
Relay — best for managing multiple accounts
Relay helps LLCs that budget by dividing cash across many accounts. Its free plan is $0 per month12 and allows you to open up to 20 checking accounts and issue up to 50 virtual and plastic debit cards per cardholder per checking account. The Grow plan costs $30 per month12 . It’s FDIC insured through its partner bank and ideal for cash-flow systems like Profit First.
American Express Business Checking — best for rewards
American Express Business Checking works well for LLCs already in the Amex ecosystem. It has no monthly fees, lets eligible customers earn Membership Rewards points on qualifying debit card purchases, and offers the opportunity to earn interest on eligible balances, subject to the current rates and account terms. Deposits are FDIC insured through American Express National Bank.13
Wise — best for simple international transfers
Wise is a fintech that is handy for businesses that make occasional international transfers. It has a $0 monthly fee with a one-off $31 setup14, and converts at the mid-market rate plus a conversion fee varying from 0.57%14 to 2%.17
Businesses that regularly hold, receive, and manage multiple currencies may prefer a platform designed for ongoing international operations rather than individual transfers.
Fees and features at a glance: LLC account comparison
Use this comparison to weigh the full cost of each option. A low monthly price means little if the foreign exchange margin or wire fees are high, so we show international costs alongside the monthly fee.
Business bank account for LLC fees vary widely, and undisclosed FX costs are noted rather than left blank. Ranking the full cost is how you find the best business checking account for LLC owners.
| Provider | Best for | Monthly fee | FX / international | Local accounts / currencies | FDIC |
|---|---|---|---|---|---|
| OFX | International payments and multi-currency | No minimum balance | No setup or transfer fees; supports international payments in 30+ currencies4 | Local account details available in USD, CAD, EUR and GBP; hold and manage 30+ currencies4 | Not a bank. Registered as a Money Services Business with FinCEN and licensed as a money transmitter (NMLS #1021624).5 |
| Bluevine | Online high-yield checking | $0 Standard; $95 Premier6 | USD; no built-in FX | USD only | Eligible for FDIC insurance up to US$3 million through partner bank sweep program6 |
| Chase | Branch access | $15 (waived for eligible customers)7 | International wire and foreign transaction fees may apply | USD only | FDIC insured |
| Mercury | Startups | $0 core plan9 | USD focused | USD focused | FDIC insured via partner banks |
| Novo | Freelancers and solopreneurs | $010 | Free ACH; domestic wires up to $3011 | USD only | FDIC insured via partner bank |
| Relay | Managing multiple accounts | $0 Starter; $30 Grow12 | USD focused | USD only | FDIC insured via partner bank |
| American Express | Rewards | $0 monthly maintenance fee13 | USD only | USD only | FDIC insured via American Express National Bank |
| Wise | International transfers | No monthly account fee; one-time US$31 setup fee14 | Mid-market exchange rate; sending and conversion fees vary by currency from 0.57%14to 2%17 | Multi-currency balances | Not a bank |
How to choose the best business bank account for your LLC
The best business checking account for LLC owners is the one that fits how the money actually moves. Work through these factors before you apply.
- Fees and minimums: look beyond the monthly fee. Compare the total cost, including any minimum balance required to waive account fees.
- The full cost of international payments: If you send or receive money overseas, factor in wire fees and foreign exchange costs. These can have a bigger impact than the monthly account fee.
- Transaction limits: check free transaction caps and cash deposit limits to avoid unexpected charges as you grow.
- Online vs branch: decide whether you need a branch for cash and cheques, or whether an online business bank account for LLC management suits you better.
- Accounting integrations: if you use accounting software, choose an account that syncs with your accounting software such as QuickBooks Online or Xero to speed up reconciliation.
- Deposit protection: understand how your money is protected, whether by FDIC insurance at a bank or by other safeguards at a fintech.
- International needs: if you pay overseas suppliers or collect from global clients, look for multi-currency accounts, a dedicated international payments provider, and tools to manage currency risk.
Choosing the right account is about finding the one that best supports the way your business manages money today and as it grows.
How to open a business bank account for your LLC
New businesses are forming constantly, with 531,423 business applications filed in June 2026 alone.15 Once your LLC is formed, opening an account is quick, and many providers let you apply fully online. Gather these documents first:
- Your federal EIN (or your SSN if you are a sole proprietor)
- Your Articles of Organization or other formation documents
- Ownership or operating agreements, especially for a multi-member LLC
- A government-issued photo ID for each owner
- Your business license, if your activity requires one
A common question is whether you can open an LLC business account with just an EIN. You’ll generally need your EIN plus formation documents and ID, not the EIN alone.
Many online and fintech providers verify these digitally, so you can open a small business bank account for LLC operations without visiting a branch.
FDIC insurance and keeping your LLC’s money secure
FDIC insurance covers $250,000 per depositor, per ownership category, per insured bank.16 An LLC’s deposits are insured separately from the owners’ personal funds, while a sole proprietor’s deposits are added together with their personal single-ownership funds at the same bank.
Some providers advertise multi-million-dollar coverage. That comes from sweep networks that spread your balance across several insured banks, extending protection beyond the base $250,000 at any one bank. It’s a useful feature, but it’s a distinct arrangement, not standard single-bank coverage.
Can you open a business transaction account from a fintech alongside a business bank account?
Yes. Many of our clients keep bank accounts for legal or borrowing purposes while using an OFX Global Business Account to save time and money on their financial operations and currency transfers.
I was recommended to use OFX, but honestly I wish I knew about it sooner. By far OFX is the most competitively priced and easiest platform we’ve ever used. The user experience and customer service have been a lot better for our finance teams to manage,” said Jonathon, co-founder of BikesOnline.
Why OFX stands out for LLCs
If your LLC moves money across borders, OFX brings your global payments and currency management into one place. Here is what sets it apart for business.
- Get paid like a local: hold and manage 30+ currencies and receive with local account details in USD, CAD, EUR, and GBP.4
- Keep more of every payment: competitive FX rates with no setup fees, no transfer fees, and no minimum balance.
- Move money faster: local payment rails rather than only SWIFT, so settlement is quicker and often same day.
- Work the way you already do: sync with QuickBooks Online and Xero, and earn cashback on eligible card spend.
- Built on trust: licensed as a money transmitter in every US state and registered as an MSB with FinCEN (NMLS #1021624),5 backed by more than 25 years of experience.
Registration takes under 10 minutes. See our business pricing for more details.
Frequently asked questions about the best bank accounts for LLCs
What bank account is best for an LLC?
There is no single answer. The best LLC bank account depends on your priorities: branch access, yield, low fees, or cross-border payments. When comparing the best banks for LLC business accounts, match the account to how your business operates.
Do you need a separate bank account for an LLC?
Yes. A separate bank account for LLC finances protects your limited liability and keeps business and personal money separate, which is essential for clean books and legal protection.
Can you open an LLC bank account online with just an EIN?
Usually you need your EIN plus your formation documents and a photo ID. Many providers let you complete the whole application online once you have the required documents ready.
What documents do you need to open an LLC bank account?
Typically your EIN, Articles of Organization, ownership or operating agreements, a government-issued photo ID, and a business license if one applies to your industry.
Is a free business bank account for an LLC worth it?
Often, yes, but check the full cost. A $0 monthly fee on a small business bank account for LLC operations is only a saving if wire and foreign exchange fees are also reasonable for how you use the account.
Can an LLC account handle international payments?
Traditional bank accounts can send international wires, but fees and FX margins add up. A multi-currency fintech account can hold several currencies and use local rails, which usually costs less for regular cross-border activity.
How is my LLC bank account taxed?
An LLC’s tax treatment depends on how it’s classified, and rules can change. Keep it high-level and check the official IRS guidance for your situation before making decisions.
Looking for an alternative to your bank?
References
- https://advocacy.sba.gov/2025/06/30/new-advocacy-report-shows-the-number-of-small-businesses-in-the-u-s-exceeds-36-million/
- https://www.sba.gov/business-guide/launch-your-business/open-business-bank-account
- https://www.irs.gov/pub/irs-wd/0235023.pdf
- https://www.ofx.com/en-us/business/global-business-account/
- https://www.ofx.com/en-us/legal/state-licensing/
- https://www.bluevine.com/business-checking
- https://www.chase.com/business/banking/checking/business-complete-banking
- https://www.chase.com/business/banking/checking/performance-business-checking
- https://mercury.com/pricing
- https://www.novo.co/business-checking
- https://www.novo.co/help/how-much-does-it-cost-to-send-a-wire
- https://relayfi.com/pricing/
- https://www.americanexpress.com/en-us/business/checking/
- https://wise.com/us/pricing/business
- https://www.census.gov/econ/bfs/current/index.html
- https://www.fdic.gov/resources/deposit-insurance/understanding-deposit-insurance
- https://transferfees.io/guides/wise-fees-explained/
OFX is licensed as a money transmitter by the relevant state regulatory agency in every US state. OFX is registered as a Money Service Business (MSB) at the federal level with the Financial Crimes Enforcement Network (FinCEN). OFX is not a bank and does not offer banking services. OFX’s services include money transfers and foreign exchange, which are not FDIC insured.
Your money and information sit behind strong protections. OFX is regulated by 50+ regulators globally, is ISO 27001:2022 certified, brings 25+ years of experience, and runs a risk-averse payout model, so funds are never paid out before they are received.
Learn more about how OFX keeps your money and information secure.